Cyprus Real Estate Market 2026: Record €6.5bn Transactions, a 65% Surge in New Apartments, and Where abuda Sits in the Premium Off-Plan Market
Cyprus real estate hit a record €6.5bn in 2025 while price growth cooled to 3.4%. New-apartment permits are up 86%, Larnaca prices up 11.7%, and the 2026 tax and title-deed reforms favour early-stage new builds. Where abuda's 1,384 available units sit in the premium off-plan market.
Cyprus Real Estate Market 2026: Record €6.5bn Transactions, a 65% Surge in New Apartments, and Where abuda Sits in the Premium Off-Plan Market
Published 12 September 2026 by Kefah Abu Gosh
TL;DR — Cyprus recorded an all-time-high €6.5 billion in property transactions in 2025 (+8%), yet official price growth cooled to 3.4% by Q1 2026 — a market that is liquid but not overheating. Developers are answering demand with volume: permits for 7,131 new homes were issued in January–April 2026 alone (+65%), 5,184 of them apartments (+86%). Foreign buyers grew 16%, with 80% of that growth in Limassol, Larnaca and Paphos. The 2026 rulebook — stamp duty abolished, SDC on rental income abolished, the trapped-buyer problem legally closed, and the EU energy directive in force — tilts the economics decisively toward early-stage, compliant new builds. In a developer market where no single company holds even a 10% share, abuda's live inventory of 1,384 available units across 75 Cyprus projects represents an estimated 23–34% of the premium off-plan inventory open to international buyers. This article sets out the data, the method behind that estimate, and what it means for investors, relocating families and holiday-home buyers.
1. A record year — without a bubble
The headline numbers for 2025 are the strongest Cyprus has ever printed. Transaction value reached €6.5 billion, up 8% from €6.0 billion in 2024; volume rose 4% to 25,600 properties. Residential real estate did the heavy lifting at €4.5 billion — 69% of the total.
The more important number is the one that didn't spike. The Eurostat House Price Index for Cyprus cooled from 6.0% year-on-year in late 2025 to 3.4% in Q1 2026. Record liquidity alongside decelerating price inflation means one thing: the market is supply-elastic. Developers are delivering enough new inventory to absorb demand without the runaway price dynamics that preceded the last correction. For an investor, that is the environment that rewards predictable appreciation and stable yield over speculative flipping — the thesis we laid out in The Alpha Advantage.
Foreign demand grew 16% to 7,255 properties, roughly two-thirds bought by non-EU nationals, and 80% of the growth landed in the three coastal districts. Macro support is solid: GDP +3.8% (provisional) and inflation at 0.8%.
2. The supply pipeline: apartments, at scale
Cyprus is restructuring its housing stock from low-density houses toward apartment blocks. Apartments accounted for 60% of the growth in 2025 transaction value and 42% of total value. Roughly one in three new homes is now bought directly from a developer, and in the coastal districts off-plan and brand-new developer stock is nearly 45% of all transactions above €350,000.
The forward pipeline, from CYSTAT building permits for January–April 2026:
Category (Jan–Apr 2026) | Dwelling units | Year-on-year |
|---|---|---|
Residential apartment blocks | 5,184 | +85.9% |
Single houses | 1,237 | +23.3% |
Mixed residential/commercial | 291 | +79.6% |
Total planned | 7,131 | +65.0% |
That is 2,915 permits (+35.1%) worth €1.67 billion in four months — an annualised run-rate of roughly 15,000–16,000 new apartments. Absorption is keeping pace: new-build sales reached €1.149 billion in H1 2026 across 3,594 units.
The product is changing too. With construction costs elevated and prime coastal land scarce, developers are densifying — replacing villa schemes with boutique blocks of 8–20 units and, in Limassol, high-rise towers. Readers of our project coverage will recognise the format: the Victoria collection in Larnaca and buildings like Elle Residences in Limassol are exactly this boutique-block cohort.
3. District by district
Cyprus is not one market. The three coastal districts run on different drivers, price tiers and yield profiles.
District | Share of 2025 value | Avg. apartment price | New-build €/m² (2026) | Investment profile |
|---|---|---|---|---|
41% | €403,000 | €4,500–€12,000+ | Executive rentals, branded residences, capital preservation | |
19% | €230,000 | €2,800–€5,500 | Residency-driven buyers, holiday lets, resort communities | |
Nicosia | 19% | €177,000 | €2,200–€4,200 | Domestic and professional rentals |
16% | €178,000 | €2,400–€4,800 | Infrastructure-driven appreciation, value entry, short lets |
Limassol — the premium anchor. Forty-one percent of national transaction value and the island's highest gross rental yields, averaging about 6.0%, driven by executive demand and a structural shortage of prime city-centre housing. Its share of the €1.5m+ luxury segment slipped from 76% to 61% as buyers diversified, and transaction volumes have stabilised — the signature of a maturing market. Limassol remains the core of any Cyprus portfolio; it is no longer where the cheapest appreciation sits. Full analysis in the Limassol Intelligence Report.
Larnaca — the value-growth corridor. Prices up 11.7% year-on-year, well ahead of the national average, from an average apartment price of €178,000. The catalysts are physical: the €1.2 billion Port and Marina redevelopment, continuous airport expansion, and the arrival of institutional-grade capital — most visibly the 350,000 sqm Foster + Partners Land of Tomorrow masterplan in Livadia. Livadia and Aradippou are converting from outer suburbs into the eastern anchors of the city. This is the "catch-up pricing" case in the Larnaca Intelligence Report, now with the numbers behind it.
Paphos — lifestyle, heritage and residency. Nineteen percent of value, and the district that expanded its luxury share most sharply — from 18% to 28% — as high-net-worth buyers shifted toward lower-density, resort-style living. Gross yields run 4.25–5.39%, seasonal outside the centre; Kato Paphos delivers the strongest year-round occupancy through combined tourist and expatriate demand — the pattern behind projects like Pafilia Gardens and Elysia Blu.
For a side-by-side of these markets against a German alternative, see Limassol vs. Larnaca vs. Berlin.
4. A fragmented developer market — and why that is the investor's real risk
Property development is 15–17% of Cyprus GDP and employs 35,000–47,000 people. The industry body's 55+ members account for more than 80% of the sector. But at the level of individual companies the market is highly fragmented: no developer holds a double-digit share of new-build supply; the top tier each command roughly 2–6%.
Two consequences follow. First, quality, financial backing and execution vary materially from one project to the next — even within the same district and price band. Second, Cyprus still has no official register defining who may operate as a developer; anyone can, which is why the industry body itself is proposing a licensing law.
For an international buyer, that is an information-asymmetry problem more than a market-risk problem. The market is sound; individual projects are not interchangeable. This is the gap curated platforms exist to close — pre-vetting developer credibility, track record and title path before capital is committed. We covered the specific checks in What Are the Real Risks of Buying Property in Cyprus in 2026.
5. Where abuda sits: an estimated 23–34% of premium off-plan inventory
abuda is a private real-estate investment platform for qualified investors. It secures pre-sale and off-market access to developments before public release, charges buyers no platform fee, and presents every project alongside AI-normalised market data, financial models and developer track records — the methodology is public.
Platform footprint in Cyprus (September 2026 audit):
District | Units in pipeline | Active projects | Representative projects |
|---|---|---|---|
Limassol | 1,299 | 30 | YOO Limassol, Elle Residences, MIR Residences, Gaia Residences, Trilogy, Limassol Greens |
Paphos | 607 | 22 | Pafilia Plaza, Eden Bay, Eden Golf, Cypress Park Living, Akamas Bay Villas |
Larnaca | 517 | 23 | Land of Tomorrow, Victoria collection, Kalamon Gran View II, Synergy, Balance |
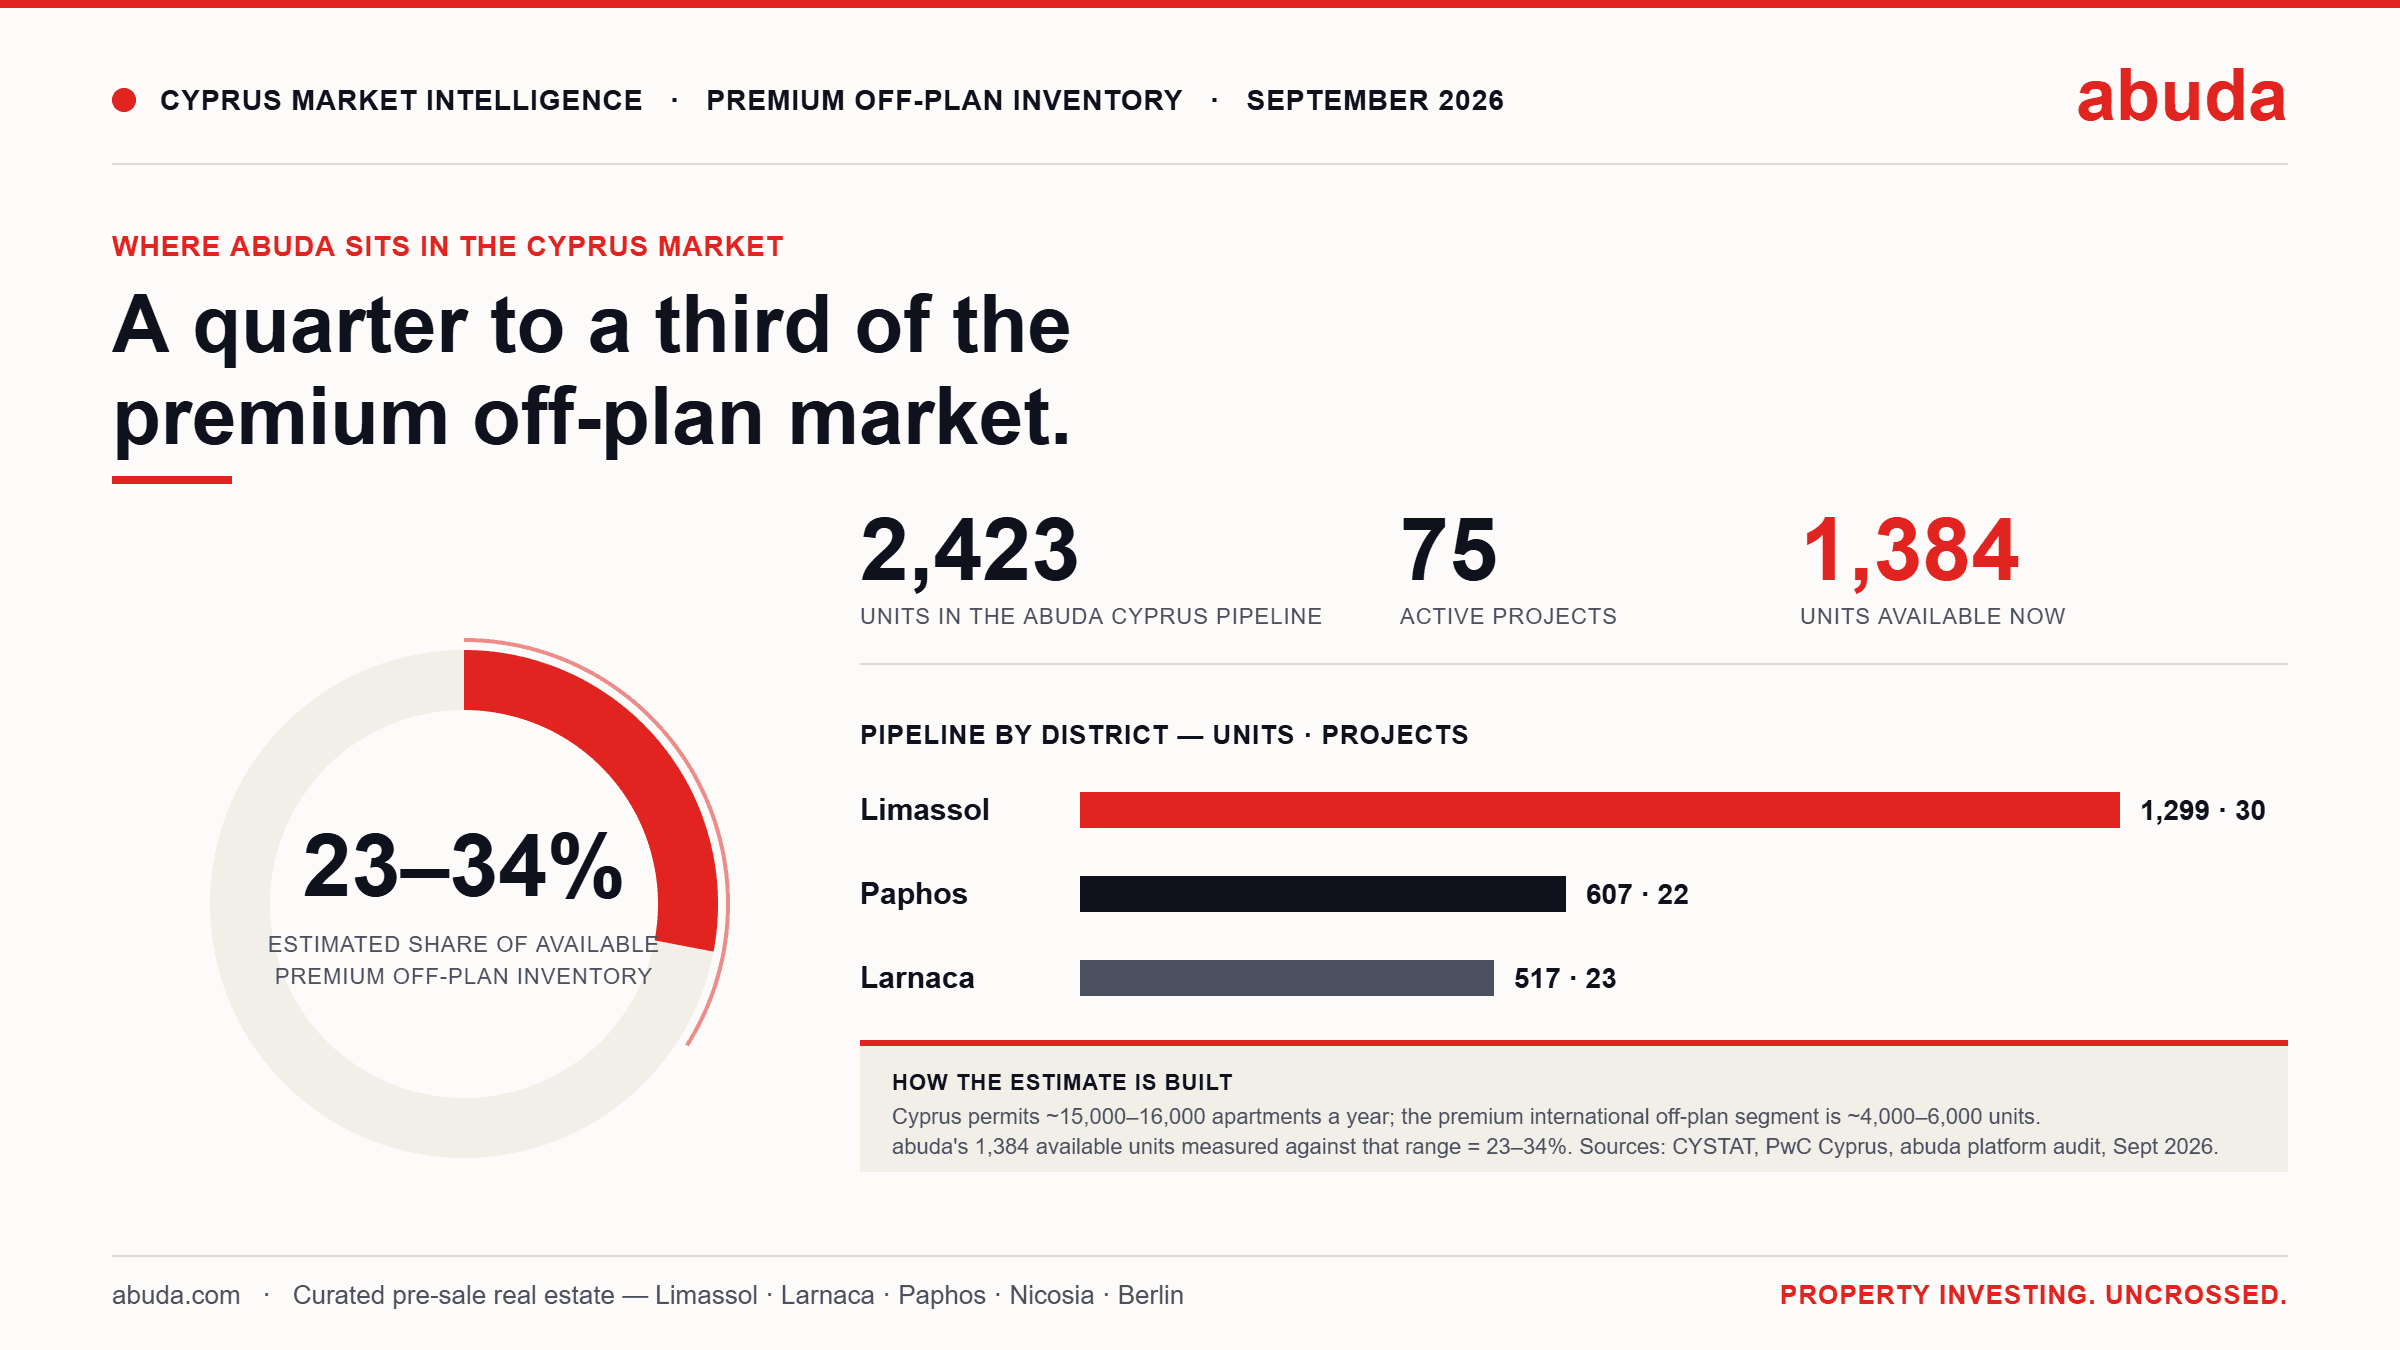
Total | 2,423 | 75 | 1,384 units currently available |
How the market-share estimate is built. Cyprus authorises roughly 15,000–16,000 apartments a year, but most are domestic, mid-market or suburban stock that international capital never sees. Applying the coastal-district observation that off-plan and new developer stock is ~45% of transactions above €350,000, the addressable premium international off-plan market is roughly 4,000–6,000 units a year. abuda's 1,384 available units measured against that range gives an estimated 23–34% share of the premium off-plan inventory open to international buyers in the coastal districts. It is an estimate, and we publish the method so it can be checked — but the order of magnitude is what matters: in a market with no dominant developer, a curated platform now aggregates a quarter to a third of the relevant inventory in one place.
What that inventory is selected for. Not generic blocks, but assets with a structural edge: branded beachfront and hillside "view-defence" in Limassol; central plots and the Livadia corridor in Larnaca; Kato Paphos walkability and residency-qualifying formats in Paphos. Every project carries a payment schedule tied to construction milestones and a documented title path — the two items the next section explains.
6. The 2026 rulebook: why it favours early-stage new builds
Tax reform (in force 1 January 2026)
Stamp duty abolished. Contracts signed from 1 January 2026 no longer pay the 0.15–0.20% tiered duty.
SDC on rental income abolished. Landlords previously paid an effective 2.25% Special Defence Contribution on rent; it is gone. Rental income is now subject only to ordinary income tax — a direct lift to net operating income.
Capital gains exemptions raised. The general lifetime exemption rose from €17,086 to €30,000; the primary-residence exemption from €85,430 to €150,000. An anti-avoidance rule now applies 20% CGT to share sales where 20%+ of a company's value derives from Cyprus property.
Corporate changes. Corporate tax rises from 12.5% to 15%, offset by abolition of the Deemed Dividend Distribution rule and a cut in SDC on actual dividends from 17% to 5% for Cyprus-domiciled individuals (non-domiciled residents remain exempt).
VAT unchanged in principle. 19% standard; a 5% rate on the first 130 m² for a primary residence held at least ten years, subject to a €475,000 value cap and 190 m² area cap. Resale property carries no VAT but 3–8% transfer fees — one more reason new build pencils better.
Title security: the Specific Performance Law, fully enforced 2026
The historic "trapped buyer" risk — a developer's umbrella mortgage blocking title transfer to a fully paid buyer — has been closed by amendments to the Sale of Property (Specific Performance) Law (N. 132(I)/2023). Every off-plan contract must now carry an Immovable Property Search Certificate dated within five working days of signing. To deposit the contract at the Land Registry, the developer and its bank must issue a "Type A" declaration committing the bank to release the specific unit from its mortgage ("Type B" receipt) once the buyer has paid 95% of the price. Developers who fail to release face fines of up to €100,000, and a contract deposited within six months secures the buyer's right to specific performance — the unit cannot be sold twice or re-pledged. This is the mechanism that makes staged off-plan payments institutionally safe; it is also why abuda insists on Land Registry deposit as step three of every purchase in our Cyprus Buying Guide.
Energy: EPBD transposed 29 May 2026
Cyprus has transposed the revised EU Energy Performance of Buildings Directive, moving from "nearly zero-energy" to zero-emission buildings by 2030. The effect is a widening green premium: competent 2026 new builds (Class A, solar, underfloor heating, high-spec insulation) will hold tenant preference and resale liquidity, while 2010-era resale stock faces rising operating costs and accelerating obsolescence. Examples already on the platform: Kalamon Ethera, Eden Coast (Class A+), Serenity Residences (photovoltaic).
7. What this means for you
Investors. The trade is regional arbitrage plus early entry: Limassol for yield and capital preservation, Larnaca for the steepest appreciation curve at the lowest €/m², Paphos for resort-community and residency demand. Enter at design or pre-sale stage, in energy-compliant buildings, with the contract deposited at the Land Registry.
Relocating families and own-use buyers. The 5% VAT primary-residence rate, the abolished stamp duty and the new title protections make a 2026 new build materially cheaper and safer than a resale — and the international-school catchments in Limassol, Larnaca (Marelia Valley in Paphos is the villa-district equivalent) are where the pipeline is concentrated.
Holiday-home buyers. Coastal boutique blocks with rooftop pools and gardens are the format the pipeline is now built around — the sweet spot between a flat and a villa, with short-let demand across all three districts and a €300,000 new-build purchase qualifying for fast-track Permanent Residency.
The full curated pipeline is at abuda.com/projects. For a briefing on any district or project: hello@abuda.com · WhatsApp +49 172 983 1161.
Frequently asked questions
Q. How big is the Cyprus real estate market in 2026? A. Transactions reached a record €6.5 billion in 2025 (+8%) across 25,600 properties; residential accounted for €4.5 billion. Official price growth cooled to 3.4% in Q1 2026.
Q. Is Cyprus property in a bubble? A. The data says no: record transaction liquidity with decelerating price inflation, because new supply (7,131 permitted homes in Jan–Apr 2026, +65%) is absorbing demand.
Q. Which Cyprus district is growing fastest? A. Larnaca — prices up 11.7% year-on-year, driven by the €1.2bn Port and Marina redevelopment and the Foster + Partners Land of Tomorrow masterplan.
Q. Which district has the highest rental yield? A. Limassol, at roughly 6.0% gross, driven by executive rental demand; Paphos runs 4.25–5.39%.
Q. What changed in Cyprus property tax in 2026? A. Stamp duty was abolished, SDC on rental income was abolished, CGT lifetime exemptions rose to €30,000 (general) and €150,000 (primary residence), and dividend SDC fell to 5% for domiciled individuals.
Q. Is buying off-plan in Cyprus safe in 2026? A. The Specific Performance Law amendments now require a search certificate within five days of signing and a bank "Type A" declaration releasing the unit from the developer's mortgage at 95% payment, with fines up to €100,000 for non-compliance.
Q. What share of the Cyprus premium off-plan market does abuda cover? A. An estimated 23–34% of available premium off-plan inventory in the coastal districts — 1,384 available units across 75 projects, measured against an addressable market of roughly 4,000–6,000 units a year.
Q. Does abuda charge buyers a fee? A. No. abuda earns from the developer side; buyers access pre-sale pricing without a platform fee.
Suggested hero image
Infographic (delivered alongside this article): abuda-cyprus-market-share-2026-infographic.svg — 1200 × 675, abuda brand DNA. Shows the 23–34% estimated share as a ring chart, the 2,423 / 75 / 1,384 headline figures, and the Limassol–Paphos–Larnaca unit split.
Cover image alt text (copy into CMS):
Infographic: abuda's estimated 23–34% share of available premium off-plan inventory in Cyprus — 2,423 units across 75 projects, 1,384 available, split across Limassol, Paphos and Larnaca.
About the author
Kefah Abu Gosh is the founder of abuda, a private real-estate investment platform for qualified investors, curating pre-sale and off-market developments across Limassol, Larnaca, Paphos, Nicosia and Berlin with AI-normalised market intelligence.
Sources
PwC Cyprus real estate press release (2026) · Cyprus Mail, "Cyprus real estate market hits record €6.5 billion value in 2025" (16 Apr 2026) · Cyprus Mail, "Cyprus approves 2,915 building permits worth €1.67bn" (10 Aug 2026) · CYSTAT building permits release (Jan–Apr 2026) · Eurostat House Price Index · Global Property Guide, Cyprus residential analysis 2026 · Cyprus Property Developers Association · Cyprus Mail, "Cyprus property body proposes new law to license developers" (20 Oct 2025) · Cyprus Tax Reform effective 1 January 2026 (B. Legal; International Tax Review; Trident Trust memo, Apr 2026) · Department of Lands and Surveys, Amendment to the Sale of Property (Specific Performance) Law · European Commission, Energy Performance of Buildings Directive · abuda platform audit, September 2026.
Internal linking map
Hubs: Projects · Limassol · Larnaca · Paphos · About · Methodology Intelligence: Limassol Intelligence Report · Larnaca Intelligence Report · Alpha Advantage · Limassol vs Larnaca vs Berlin · Cyprus property risks 2026 · Cyprus Buying Guide · REALTYon Cyprus 2026